Accountancy Saint-Paul
United States Tax and FATCA Compliance
FATCA
Since 2011, FATCA has required Americans to report foreign assets to the IRS annually, and since 2014 their foreign financial institutions as well, with non-compliance penalties set disproportionately high relative to the underlying tax exposure. In practice, foreign tax credits, treaty-based exemptions, and income exclusions available to residents abroad can substantially reduce, and in most cases eliminate, US tax liability. What matters is avoiding penalties through precise, timely compliance.
Why File?
Penalties for undisclosed foreign accounts can exceed $16,000 a year, and willful failures can cost half the account. Undeclared foreign entities carry penalties starting at $10,000 per form, per year. Unpaid tax debts over $66,000 can cost you your US passport.

Who?
American citizens and green card holders must file a US tax return each year their gross income reaches $16,100 (single; $5 if married filing separately), even if it is all excluded, or their self-employment income reaches $400.
Additional reporting requirements apply if foreign account balances together exceeded $10,000 at any point during the year, if one owned 10% or more of a company, partnership or other entity based outside the United States, or if one held foreign-domiciled investment funds.
This last category, known as PFICs, includes most ETFs and mutual funds domiciled outside the US, wherever purchased, and presents a stark choice between annual tax on unrealized gains and tax at the highest rates plus a compounding interest charge when you sell.

When?
Americans living abroad get an automatic two-month extension, to June 15, to file their returns.
FBARs are filed separately with FinCEN, due April 15 and automatically extended to October 15.

What to do?
The IRS will not impose penalties when the absence of liability is properly reported on a late return. Even if you have never filed, we can in many cases eliminate your US tax liability retroactively by claiming unused exclusions and foreign tax credits.
If you haven't already been contacted by the IRS, you may still qualify for penalty relief programs such as the Streamlined Foreign Offshore Procedure, which waives penalties for eligible non-willful taxpayers abroad.
All you have to do is file
Americans living in high-tax countries will typically owe no US income tax on foreign income. You just have to file.
Accountancy SAINT-PAUL
We prepare US returns for taxpayers who are subject to two (or more) tax regimes. We seek the best overall result, informed by obligations to the other tax regime(s) our clients are subject to. We do not prepare non-US (resident country) tax returns.
We serve clients throughout Europe. Our workflow is entirely electronic, all casework can be completed online, regardless of your location. Data is protected by bank-grade encryption in transit and at rest. Access is tightly restricted. Client files are never offshored or outsourced. All returns are prepared by in-house cross-border specialist Enrolled Agents based in Western Europe.
We accept new clients on a case-by-case basis. To inquire, please use the contact form to schedule an introductory call. Tax advice is protected by practitioner-client privilege under IRC §7525 in civil federal tax matters.
Unsolicited calls not accepted.
The Firm
Returns are prepared by Enrolled Agents admitted to practice before the Internal Revenue Service, with decades of experience handling complicated foreign assets and entities. All our Enrolled Agents are also Certified Acceptance Agents.
Practice is governed by Treasury Circular 230, with an EU representative designated under Article 27 GDPR. We are an IRS authorized e-file provider.
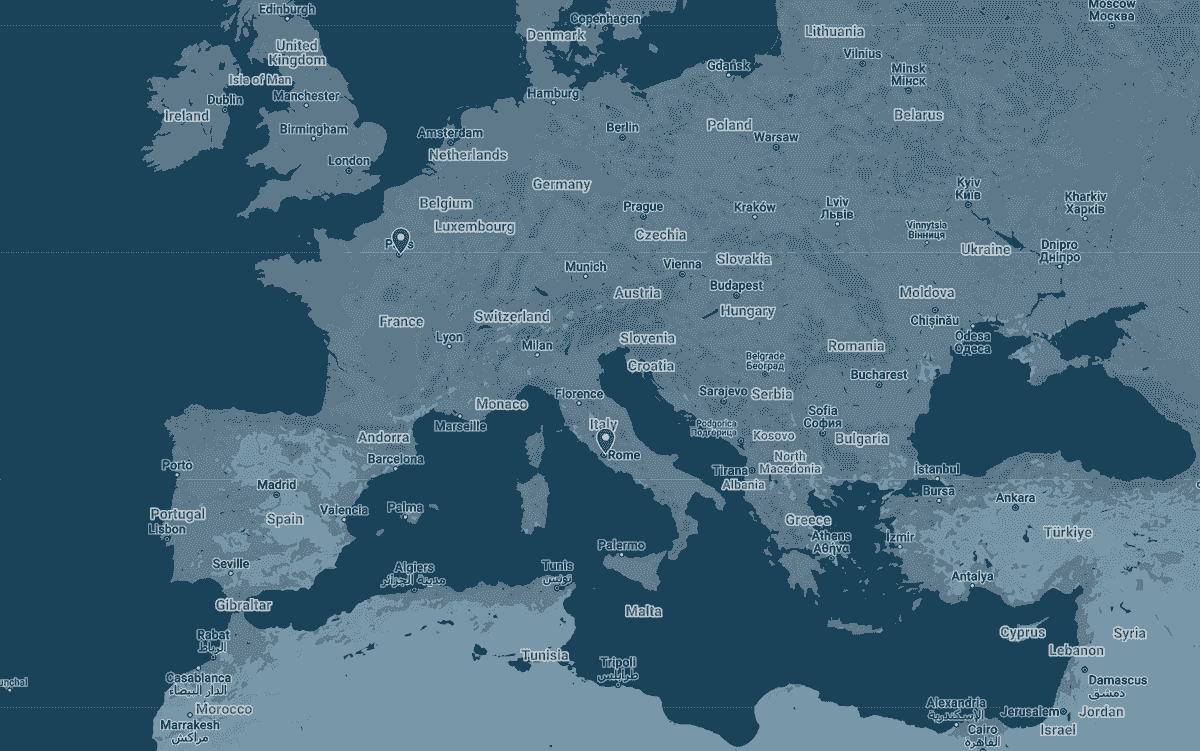
France
+33 1 87 65 01 00
by appointment
16 Place de la Bourse
75002 Paris
Italy
+39 06 4754 2775
by appointment
Piazza Mincio, 2
00198 Rome
Switzerland
+41 22 501 75 17
managed remotely
CONTACT
To discuss your case, our process, likely outcomes, requirements, etc. please use the contact form below. For complex cases, we'll reply with options to schedule a phone conversation.
You can also email: clientservices@accountancysaintpaul.com
We do not prepare resident country tax returns.
We look forward to meeting you. Tax advice is privileged under IRC §7525. English spoken.
Pricing
There is no charge for the eligibility analysis. Pricing is by form, and each form's price includes the analysis behind it. We employ additional forms beyond those required only when their use activates additional credits, exclusions, exemptions, et cetera, and there is a net financial benefit to the taxpayer. Tax planning, forecasts and IRS representation are on retainer.
Typical Results by Income Category
AMERICANS IN FRANCE
Summary: In France you'll pay the same rates as anyone else living in France, which usually leaves no tax left to pay in the states. There are, however, a number of generous provisions for US pensions in the Franco-American tax treaty.
Salary Income: $400k
(US or foreign source)
A first tranche of earned income is excludable; Remaining US liability cancelled with credits for accrued French income tax and CSG/CRDS.
Result: 0 US Liability
Liquid Assets: $2MM
(US or foreign accounts)
The US does not have a wealth tax. Assets are non taxable, but when held in accounts outside of the US, each foreign account will need to be declared on FBAR and form 8938. Directly held real property is exempt from reporting.
Result: 0 US Liability
Realized Gain: $100k
(US or foreign broker)
Gains are taxed in France. Credit for accrued French income tax and CSG/CRDS is applied to cancel US capital gains tax. Unrealized gains remain untaxed unless held in PFICs
Result: 0 US Liability
Portfolio Income $40k
(US or foreign)
Bond, dividend and interest income is taxed in France. Credits for accrued French income tax and CSG/CRDS applied to cancel US tax.
Result: 0 US liability
Net Foreign Rental Income €60k
Rental income is taxed in France. Credits for accrued French income tax and CSG/CRDS are applied to cancel US tax.
Result: 0 US liability
Problem Areas
- Severance payments untaxed by France
- 3.8% NIIT on passive income can't be offset with foreign tax credits
AMERICANS IN ITALY
Summary: The availability of heavily discounted impatriate tax regimes enables real tax savings relative to other residents of Italy. This complicates the foreign tax credit calculus, but you are likely to pay less tax overall than if you stayed home.
Salary Income: $465k
(US or foreign source)
Italy's impatriate regime reduces earned income taxable in Italy by 50%. The reduced Italian tax can then be used to offset US income tax.
Result: 0 US Liability for incomes less than $465k
Liquid Assets: $2MM
(US or foreign accounts)
The US does not have a wealth tax. Assets are non taxable, but when held in accounts outside of the US, each foreign account will need to be declared on FBAR and form 8938. Real property is exempt from reporting.
Result: 0 US Liability
Realized Gain: $100k
(US or foreign broker)
Gains are taxed in Italy. Credit for accrued income tax is applied to cancel US capital gains tax.
Result: 0 US Liability
Bond Income $40k
(US or foreign)
Government Bond income is taxed at a reduced 12.5% rate in Italy. Even so, with the standard deduction and credits, there is often enough to work with to cancel US liability on passive income.
Result: 0 US Liability for up to $185k of bond income
Retirement Income: $200k
Italy taxes IRA distributions and pension income. Credit for Italian tax paid is applied to cancel US liability.
Result: 0 US Liability
Problem Areas
- Self-Employment Tax (FICA) - Americans pay social security to the US, dual citizens can choose social security regime
- 3.8% NIIT tax on passive income for high earners can't be offset with foreign tax credits
Questions & Answers
The Internal Revenue Code is complicated and the answers below are written to be general enough to set basic expectations in common situations, but they reflect careful application of the law by proper choice of form and method. We describe the result not the process. If you believe you are subject to exceptional circumstances and/or want to learn more about the details and how they could apply to you, send us a message or contact your tax advisor.
For US citizens living abroad, tax residency is the key determinant of where income is taxed, not the income's source or the payer's location. While Americans are always subject to US tax regulations on their worldwide income, their country of residence also has the right to tax that same income,...The Streamlined Foreign Offshore Procedure offers a limited-time opportunity to resolve past non-compliance for U.S. taxpayers living abroad. By filing three years of tax returns and six years of FBARs, qualified individuals can avoid substantial failure-to-file penalties, which can easily reach...W-9 is the form banks use to collect US citizen client's social security numbers in order to satisfy their FATCA reporting requirement. If you are current on your US tax and FATCA obligations and want to keep your account open, there is no reason not to return the completed w-9. If you are...American Citizens or Permanent Residents who declare earned income and have American Citizen children under 17, with social security numbers, are eligible to receive child tax credits with a maximum value of $2000 per qualifying child in 2025. The refundable part of the credit, ACTC, is worth up...The account values reported on the FBAR are not taxable income. The United States does not have a wealth tax. Only the interest, dividend or investment income from foreign accounts is taxable, and generally escapes US tax by the application of a credit for the foreign taxes paid on the same...It many cases it can actually be helpful to have a so-called "Non-Resident Alien" Spouse. The primary advantage is that the spouse's income is neither reported nor taxable in the United States.Services
UNITED STATES TAX COMPLIANCE FOR ANY BUSINESS OR INDIVIDUAL SUBJECT TO THE US TAX SYSTEM
INDIVIDUALS
- US tax reporting of foreign income, foreign assets, foreign businesses, foreign pensions and tax-favored accounts, foreign inheritance & gifts, and foreign gains (IRS Form 1040)
- FATCA/FinCEN reporting for individuals (W-9, W-8BEN, FBAR, FinCEN 114, 8938)
- Tax projection and forecasting
- Exemption of income by treaty (8833)
- Passive foreign investment companies and non US funds (PFIC 8621)
- Nonresident and Dual-status returns (1040NR, dual-status)
- Nonresident alien spouse complications (NRA)
- US tax ID applications for foreign persons (ITIN W-7)
- Streamlined foreign offshore procedures (14653)
- Streamlined domestic offshore procedures (14654)
- Accidental Americans (SFOP 14653)
- Renunciation, relinquishment and green card surrender (8854, DS-4079)
- Relief procedures for certain former citizens (8854)
BUSINESSES
- US corporate and partnership tax (1120, 1120-S, 1065)
- American control of foreign corporations (CFC 5471)
- American control of foreign passthrough entities, partnerships, and real estate companies (FPE 8858, 8865, 8832)
- Foreign corporations with US source income (1120-F)
- Foreign-owned US corporations and LLCs (5472)
- FATCA classification and reporting for foreign individuals and entities (W-8BEN, W-8BEN-E)
- 401k plans abroad (5500)
- US TIN applications for foreign corporations (EIN SS-4)
- Reconciliation to US GAAP
- Bureau of Economic Analysis - BEA benchmarks (BE-10A, BE-10B, BE-10C, BE-10D, BE-10 Exemptions)

VIGILANTIBUS NON DORMIENTIBUS ÆQUITAS SUBVENIT.
Equity favors the vigilant, not those who sleep on their rights.
Copyright © 2026 Accountancy Saint-Paul, LLC. All rights reserved. No part of this webpage may be reproduced, distributed, or transmitted in any form or by any means without the prior written permission of the copyright owner. Legal action may be taken if unauthorized use is identified.